The Digital Nomad's Guide to Managing Money, Building Savings, and Breaking Free Financially
(Photo: Dave Weatherall)
*Note: This is a guest post submitted to All Things Wanderful by Lucy Reed, creator of GigMine.
For full-time digital nomads, money can feel unpredictable even when work is going well. The core tension is that location-independent income often arrives unevenly, whereas bills, taxes, and commitments keep showing up on schedule. Add in common remote work financial planning gaps, such as unclear baselines, blurry priorities, and inconsistent routines, and it’s easy for progress to stall. What’s more, managing travel expenses turns everyday spending into a moving target, with prices, currencies, and “one-time” costs popping up again and again.
Steadier financial security is attainable, however, and it starts by identifying these financial security challenges clearly — and then tackling them head on.
Set Up a Nomad-Proof Money System
This process helps you turn uneven income and shifting travel costs into a simple system you can run anywhere. It matters because a few repeatable habits can reduce money surprises and keep your savings growing even when your schedule changes.
Build your “baseline budget” from real income
Start by totaling what actually hits your accounts, then set spending targets from that number, not your best month. A budget works best when you reflect your real monthly income and plan around a conservative average. Keep it simple with three buckets: needs, travel and fun, and future you.Add a travel buffer and automate an emergency fund
Choose a starter goal you can reach quickly, such as one month of essentials, then expand it over time. Automate transfers right after you get paid so the fund grows even when you are busy moving around. Treat this as “surprise-proofing” for medical costs, gear replacement, and sudden rebooking.Diversify income with one backup stream
Pick one additional revenue source that fits your skills, such as a retainer client, a small digital product, or part-time consulting. Set a small weekly target and ship something consistently rather than chasing a big launch. The goal is stability, so your budget does not collapse when one client pauses.Choose banking that works across borders
Use at least two accounts: a spending account for daily purchases and a separate savings account for your emergency fund. Confirm your cards are reliable for international use, fees are clear, and you have a backup card stored safely. Turn on transaction alerts so you catch problems fast.Invest simply and review monthly
Start with a small, automatic investment amount you can keep paying through slow months, then increase it after your emergency fund is on track. Keep decisions boring: focus on consistency, not timing the market, and schedule one monthly check-in to adjust your budget, savings, and contributions.
Set Up a “Travel-Proof” Business Foundation in One Afternoon
Once your money system is running smoothly, the next step is making your day-to-day business admin easier to manage from anywhere. An all-in-one business platform can pull key tasks into one place so you’re not juggling tools across time zones. Look for something that lets you invoice clients, log and manage expenses, and track income as it comes in, so you always know what you earned and what you can safely spend. Using a single hub like ZenBusiness can help you stay organized and reduce the chance that missed paperwork or messy records throws off your financial security while you travel. With the basics centralized, it’s much easier to build simple weekly and monthly habits that keep everything on track.
Weekly Money-Confidence Rituals for Nomad Life
When you move often, small money check-ins prevent minor slips from turning into stressful surprises. These habits keep cash flow, savings, and credit pointed in the right direction so you can travel and work with more confidence.
Weekly Expense Sweep
What it is: Review every purchase and categorize it before the week ends
How often: Weekly
Why it helps: You spot leaks fast and adjust spending early.
Automatic Safety Net Transfer
What it is: Route a fixed amount into an emergency savings account right after you get paid
How often: Per payday
Why it helps: Your buffer grows even when income fluctuates
Two-Number Cash Flow Check
What it is: Record this week’s income total and total spending in one note
How often: Weekly
Why it helps: Trends become obvious without a long spreadsheet session
Monthly “Future You” Review
What it is: Set goals for savings, taxes, and debt, then pick one next step
How often: Monthly
Why it helps: You keep priorities clear despite changing routines
Credit Health Minute
What it is: Check balances and due dates, then schedule payments to avoid late fees
How often: Weekly
Why it helps: Strong credit expands options for housing, cards, and emergencies
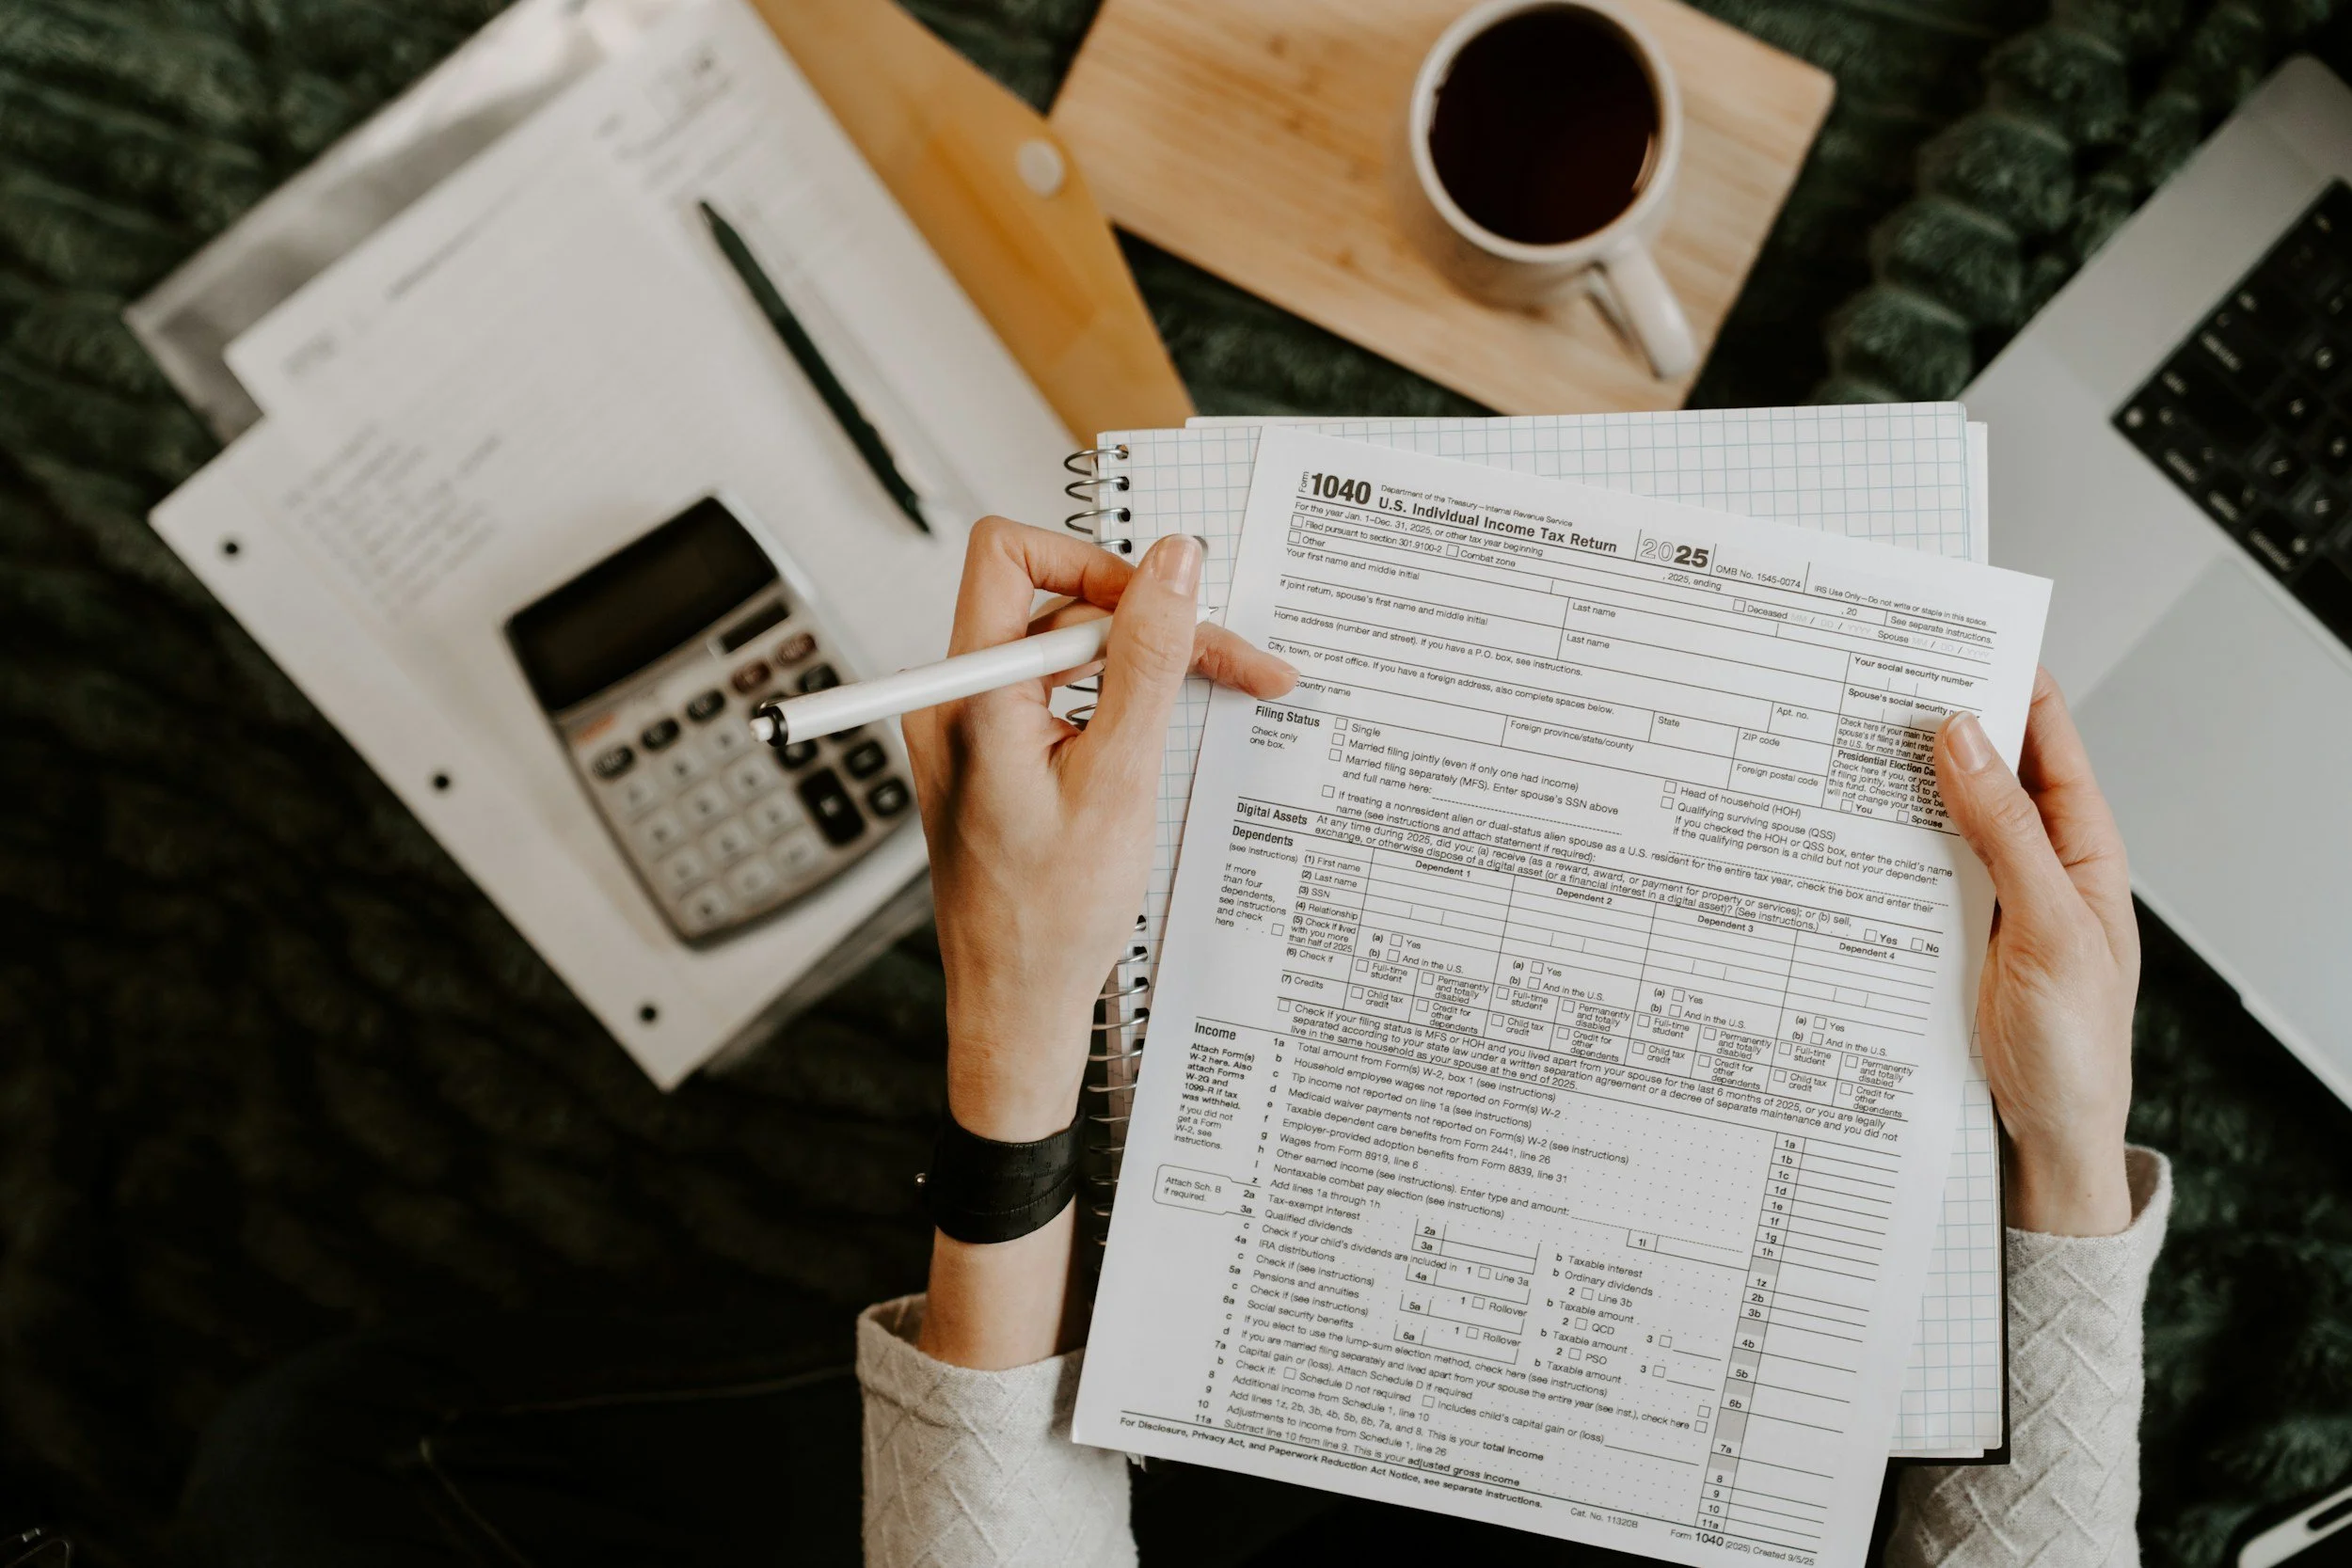
(Photo: Kelly Sikkema)
Money Questions Digital Nomads Ask Most
Q: How do I file taxes if I’m living abroad most of the year?
A: Start by confirming your tax residency rules and your filing obligations back home, since citizenship and residency can both trigger requirements. Keep a simple folder of income invoices, bank statements, and travel dates so you can prove where you were. If things get complex, a cross-border tax preparer is often worth the fee.
Q: What’s the simplest way to manage currency exchange without losing money?
A: Use one “home base” account for savings and taxes, then a low-fee card for daily spending in local currency. Convert in fewer, larger batches when rates look reasonable instead of doing tiny exchanges constantly. Track your real costs using one default currency so your budget stays clear.
Q: How do I choose health insurance that actually works internationally?
A: Look for coverage that includes outpatient care, hospitalization, emergency evacuation, and clear rules for pre-existing conditions. Confirm whether you need to pay up front and submit claims, and save emergency numbers offline. Keep a small medical deductible fund so you are not forced onto a credit card in a crisis.
Q: Can I still plan for retirement if my income is irregular and I move a lot?
A: Yes, automate a percentage transfer whenever you get paid, even if it is small. A planning shortcut like the 4% rule can help you estimate a target number and stay motivated. Also budget for healthcare, since one-third of healthcare expenses in retirement can come out of pocket on average.
Q: How can I avoid scams when booking housing, coworking, or gigs abroad?
A: Treat urgency as a red flag, and never send money by wire or crypto to “hold” a place. Pay through platforms with dispute options, verify identities on a second channel, and screenshot terms before you click pay. If a deal feels unusually perfect, slow down and ask for proof.
Turn Nomad Income Into Steady, Long-Term Financial Resilience
Living on the move makes money feel slippery: income can swing, rules change by country, and one mistake can ripple fast. The way through is a steady, systems-first mindset, applying financial strategies with simple routines and clear decisions instead of constant firefighting. Over time, that builds long-term financial resilience, sustaining income stability and real confidence in money management while keeping the lifestyle flexible.
Stability comes from repeatable systems, not perfect timing. Choose one 30-day money move and start today by setting it up once, then checking it weekly. That consistency supports an empowered digital lifestyle that can grow with changing plans, places, and priorities.